Views
Blackstone is a fee machine wearing a buyout firm as a costume.
Record AUM, record fees, a 25% dividend bump, and $414 million of net realisations. The fee machine is magnificent. The exit machine is still in the shop.

Views
Record AUM, record fees, a 25% dividend bump, and $414 million of net realisations. The fee machine is magnificent. The exit machine is still in the shop.
Views
Legal sources define the TSA as a contract. Operators experience it as a countdown clock. What a TSA covers, what it costs, and why the exit is the first value-creation deadline of a carve-out hold.
Views
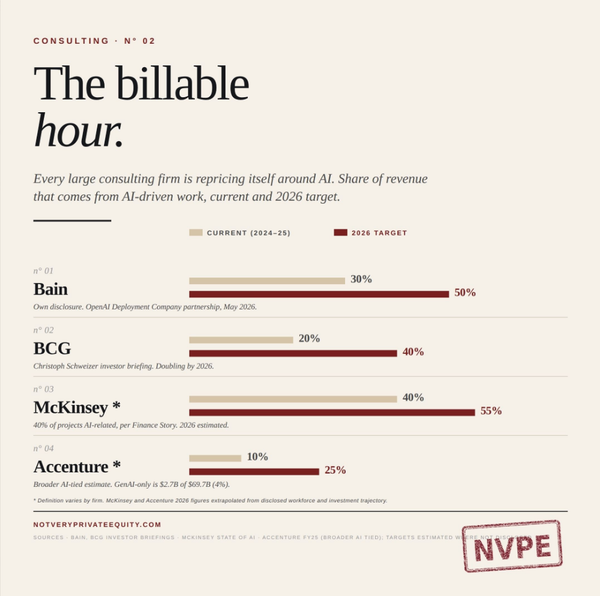
Once as strategy. Then again as AI transformation. Bain wants 50% of revenue from AI-driven work by 2026. BCG is aiming for 40%. McKinsey is already calling 40% of projects AI-related. Accenture is doing what Accenture does best, turning it into an industrial process with a very large
Views
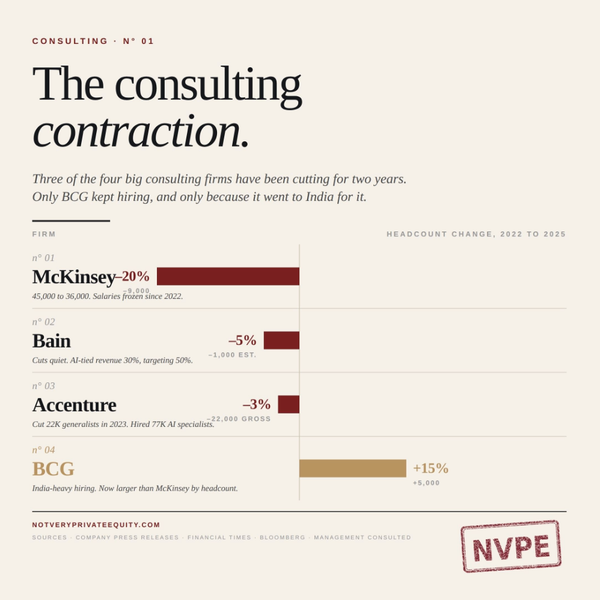
For a decade, the model was beautifully simple. Hire armies of clever generalists, put them in airport lounges, sell consensus back to executives at partner rates, then call the PDF proprietary. Now the pyramid has a leak. McKinsey has reportedly dropped from more than 45,000 people to around 40,
Views
From the outside, progress looks loud. New strategy. New leader. New initiative. New dashboard. New transformation programme with a confident name and a board update full of arrows heading in the correct direction. From the inside, real progress is usually much quieter than that. It is boring. Repetitive. Easy to
Views
Private equity returns are getting harder. More competition. More capital. Higher entry multiples. Longer hold periods. Less multiple expansion doing the heavy lifting. More pressure to actually create value, which is awkward for an industry that spent a very long time confusing a rising market with genius. And what has
Views
Private equity keeps responding to LP pressure in the same way. More slides. More dashboards. More portfolio colour. More commentary. More words spent describing things in ever finer detail without saying the one thing everyone is actually trying to work out: What is not working. That is the conversation LPs
Views
Private equity is one of the least transparent corners of finance. That is not an accident. It is a feature. The industry likes the opacity because opacity is useful. It keeps the marks private. It keeps the fee structures fuzzy. It keeps the portfolio company pain contained. It keeps LPs
Views
Most private equity firms have a diversity problem they do not talk about. Not gender. Not race. Cognitive diversity. The industry is full of people who look different enough for the website and think almost exactly the same. Same schools. Same training. Same career tracks. Same incentives. Same pattern recognition.
Views
You bought a customer acquisition machine with vans, ladders and a claims history. Unfortunately, your diligence team spent most of its time looking at the vans. Most PE firms still diligence home services like the business is the trade on the sign. Roofing company. Car wash. Gym. Auto shop. QSR.
Views
If I were building a deal sourcing engine in 2026, I would not begin by hiring more associates. I would build a system that finds off market opportunities before the bankers do. Because most firms still call it sourcing when what they really mean is reacting slightly faster to the
Views
The deal team that sources an investment should not be the same team that monitors it. That sounds obvious. In private equity, it somehow is not. The same people who got excited about the deal, won the internal argument, pushed the valuation, sold the thesis, and assured everyone the risks