
Apollo hired three managing directors. Carlyle supplied one of them.
Apollo hired three managing directors, one of them from Carlyle. Advent's head of tech strategy now works at the OpenAI venture Advent helped fund.

Apollo hired three managing directors, one of them from Carlyle. Advent's head of tech strategy now works at the OpenAI venture Advent helped fund.

GTCR and Elliott are paying $7.75 a share for CCC. Advent sold its final stake last November at $7.79, down from a $10 SPAC-era price.

Proofpoint will pay $49.75 a share for Varonis, 52% above the June close. The multiple is 53 times free cash flow, and the first-half cash flow fell.

Fee-generating assets rose €40bn in the quarter. Strip out the Coller acquisition and the gain is about €6bn.
Watch Point Capital has a one-page website and two founders from Madison Dearborn and Platinum Equity. Here is what we can say about the new defence-focused firm.
GP financing is a loan or preferred instrument provided at the manager level, to the general partner, the management company or a sponsor affiliate, rather than to the fund. It is secured on what those entities and their owners actually hold, which means equity in the management company, the right
I would ask which level of the spectrum you are actually on. Because most portcos think they are a 4. They are a 2. And the gap between those two numbers is where the write-down lives. I have sat in enough board meetings where the CEO confidently describes their
I'd start by killing the theatre. Most operating models are built backwards. There's an ops team that is really a reporting team. There's a "value creation" function that is one person, a recycled PowerPoint, and a heroic ability to say "cross-
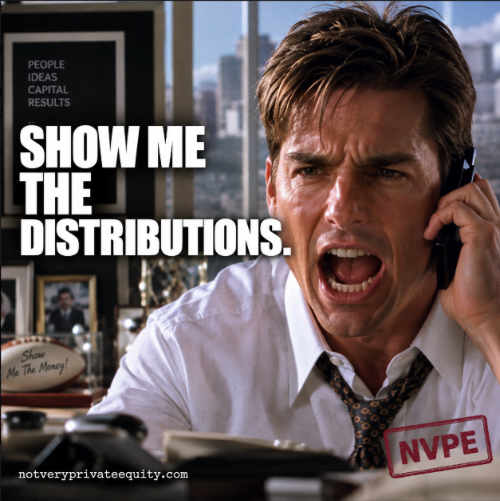
Saves everyone forty slides on why the portfolio is performing magnificently despite the absence of any money. The valuations are robust. The assets are exceptional. The exit pipeline is encouraging. Lovely. The pensioners have asked whether they can spend the appendix. Private equity gets paid to be patient. Fair enough.

A lot of LP meetings are no longer really about communication. They are about stage management. The deck is polished. The messaging is tight. The bad news has been moved three clicks deeper into the appendix. The winners get a cinematic retelling. The problems get translated into phrases like timing,
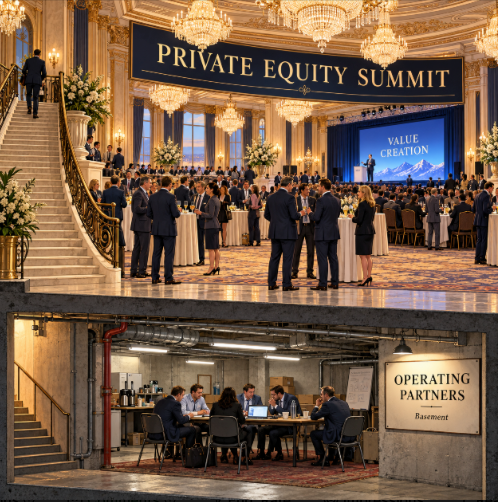
“Value creation” gets top billing on the main stage. Operating partners get a separate room, a different floor, sometimes an entirely separate event. The industry has managed to make the people responsible for delivering the investment thesis a fringe attraction. Quite an achievement. And giving operating partners their own conference

AE Industrial lost two partners to company jobs. Everyone else was hiring operators. Senior moves at the 200 largest US PE firms, week to 13 October.
Views
The re-up conversation has changed. It used to be anchored around what you returned. Track record. DPI. TVPI. Loss ratio. Attribution. Vintage year context. Whether the exits looked heroic because you created value or because the market was briefly behaving like a drunk uncle at an auction. That still
Views
For two weeks after every major PE conference, LinkedIn becomes unusable in a very specific way. Panel photo. Handshake photo. Lobby photo. Dinner photo. Candid networking photo that was clearly taken with the strategic intent of a small military operation. Then the captions arrive. "Honoured to share the stage
Views
Same product. Same process. More exciting valuation expectations. CIMs, board decks, presentations. Everything must now be “AI powered”, “AI enabled” or “AI first”. God forbid you’re just profitable. Management needs a roadmap. The sponsor needs a portfolio story. The banker needs something sexier than “well run distribution business”. So
Views
Proprietary technology. Proprietary data. Proprietary processes. Then you get access. The technology is Salesforce with some custom fields. The data is a purchased contact list. The process belongs to Dave. Dave has left. Bankers love this word. The competitive advantage it implies is considerably harder to find. “We own it”
Views
Twenty-five books, from Barbarians at the Gate to the critics the industry would rather you skipped. What to read, and what to leave on the shelf.
Life
Meta VR Glasses weigh 100 grams, cost $1,299.99 and ship in spring 2027. The display is the best Meta has built. The field of view, the empty box and the $8.6bn first-half loss are the rest of the story.
Life
New sign-ups to ChatGPT Pro $200 are paused. Existing users keep it, everyone else gets the $100 tier. A company only rations a product when the price was wrong.
Views
Every private equity firm says talent is a competitive advantage. Then most go to the same headhunters, with the same job descriptions, to hire from the same pool of people who have already worked at the same banks, same consultants, same funds, same schools, and occasionally the same emotionally repressed
Views
A magical version. A temporary version. A version that lasts roughly forty-eight hours, or until Monday morning. On the panel, the firm is operationally focused. On Monday, the operating partner has missed the last three board meetings because nobody quite decided whether they were necessary, optional, or mostly decorative.
Views
Every conference list is a calendar. This one tells you which rooms are full of operators, which are full of the people selling to them, and which three are worth the flight.
Views
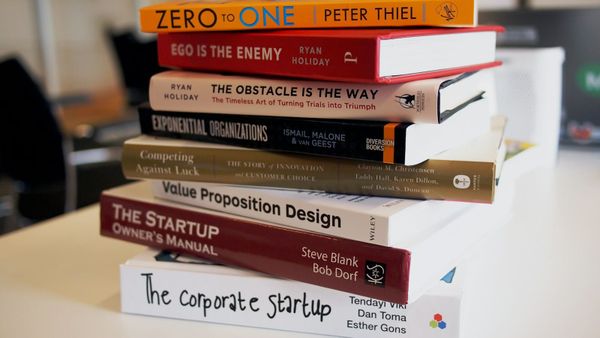
The best books for PE operating partners, grouped by the job each one does, from capital allocation to running the company. Plus the shelf to skip.
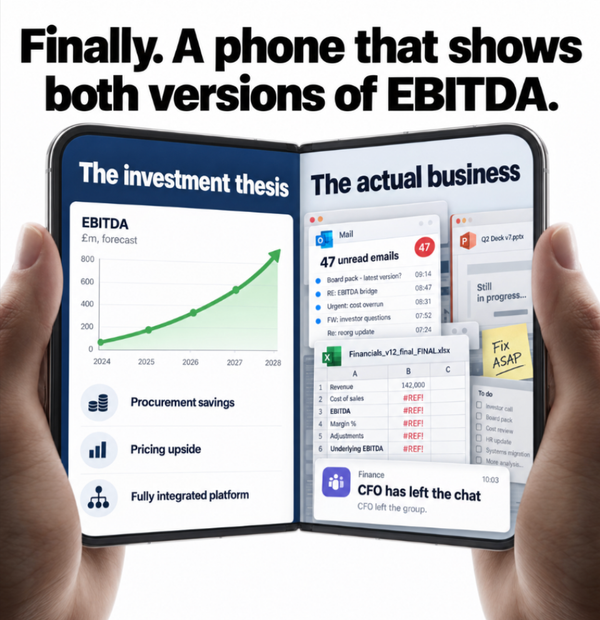
Views
The founder makes every decision. The systems don’t talk to each other. Pricing is mostly instinct. The finance team closes the month through an act of collective faith. All spotted in diligence. All described as “opportunity”. Then the deal closes and the same things become management failures. Marvellous. We’